Career Opportunities at QFAB

Career Opportunities at QFAB – Qatar Fabrication Company W.L.L.

(Blue Collar Positions Available)

Take the next step in your professional journey with a leading organization in Qatar’s industrial sector. We are pleased to announce multiple openings for skilled blue-collar professionals at Qatar Fabrication Company (QFAB), offering competitive benefits and long-term career growth.
Available Positions:
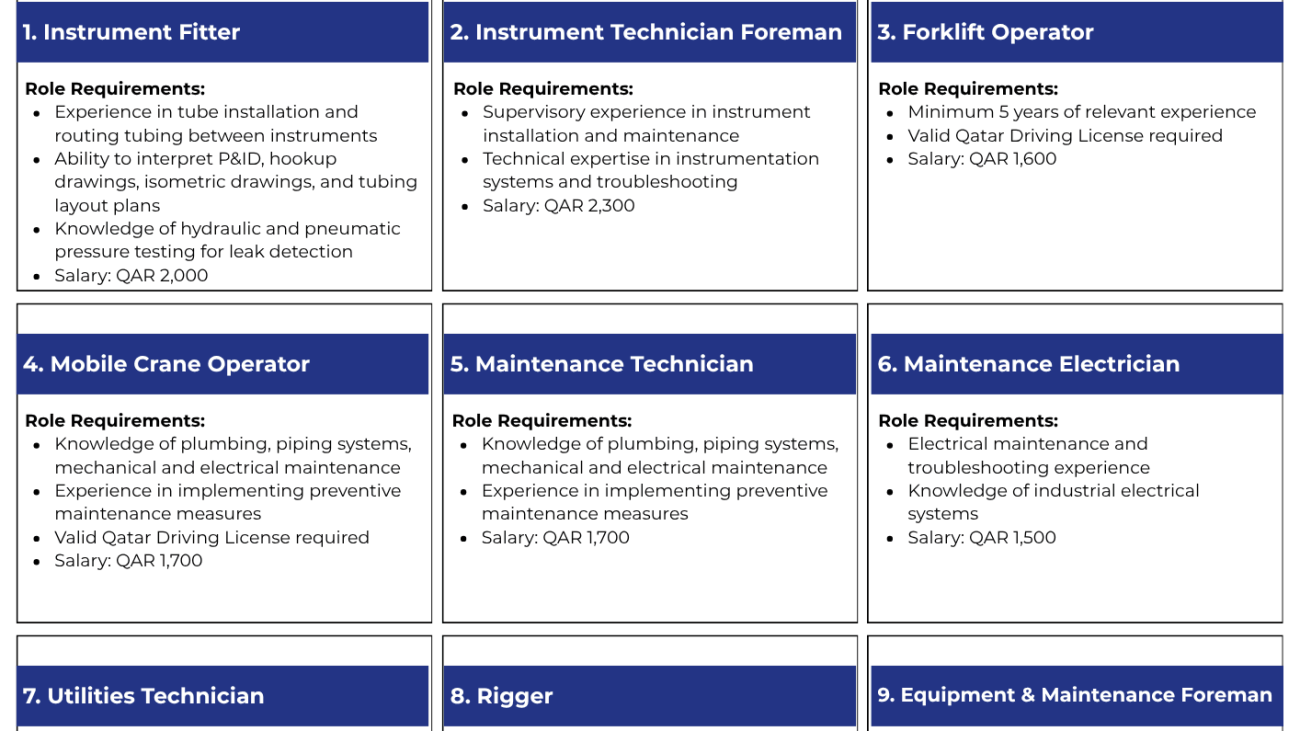
We are currently seeking qualified candidates for the following roles:
Rigger
Forklift Operator
Mobile Crane Operator
Maintenance Technician
Maintenance Electrician
Equipment & Maintenance Foreman
Utilities Technician
Instrument Filter
Instrument Technician Foreman
Employment Package Includes:
đŸ’” Competitive Tax-Free Salary – Attractive compensation paid in Qatari Riyals
🏠 Free Accommodation – Comfortable and well-maintained housing
đŸČ Free Meals & Transportation – Daily meals and commuting fully covered
✈ Return Air Ticket – Paid round-trip flight to home country every two years
đŸ–ïž Paid Annual Leave – 24 days of paid leave per year
📄 Full Visa Sponsorship – We handle all visa and work permit processes
How to Apply:
Ready to advance your career? Submit the following documents to careers@manconint.com:
Updated CV with detailed work history
Copies of relevant educational and professional certificates
Clear passport copy
Please use this email subject format:
Application for [Position Title] – [Your Full Name] Example: Application for Forklift Operator – Ahmed Khan

Join a dynamic workplace in Qatar’s growing industrial sector. Apply now and build a rewarding career with QFAB.

Contact Information:
📞 Phone: +92 333-440-2452
📧 Email: careers@manconint.com
🌐 Website: www.manconint.com

DeFi Bridges Beyond the Buzz: How Relay Bridge Fits into Multi-Chain Finance

A common misconception is that a DeFi bridge simply “moves” coins from one blockchain to another. In reality, blockchains do not share one universal state, and an asset usually cannot be picked up on Ethereum and dropped directly onto Polygon. A bridge coordinates events across separate networks: one side is locked, burned, or otherwise accounted for, while the destination side releases or represents value. That distinction matters because the bridge is not merely a faster payment lane. It is a risk-management system connecting different consensus rules, liquidity pools, smart contracts, and fee markets.

Relay Bridge is best understood as a cross-chain aggregator for decentralized finance rather than as a single-purpose token tunnel. Its stated role is to connect assets, data, and liquidity across heterogeneous networks. For users in the United States, that can mean moving capital between Ethereum, Binance Smart Chain, Polygon, Avalanche, and Huobi Eco Chain to reach a particular lending market, decentralized exchange, or yield strategy. The practical attraction is obvious. The less obvious point is that every additional chain expands both the opportunity set and the number of assumptions a user must trust.

From isolated chains to multi-chain DeFi

The first generation of DeFi was largely organized around individual ecosystems. Ethereum supplied deep liquidity and a broad developer base, but high demand could make routine transactions expensive. Other networks emerged with different trade-offs: lower fees, alternative execution environments, faster settlement expectations, or specialized communities. Bridges developed because liquidity was fragmented. A trader might hold an asset on one chain while the best market, collateral opportunity, or application was operating on another.

This historical evolution explains why “multi-chain” is more than a marketing label. It describes a coordination problem. A cross-chain transfer has to account for the source transaction, confirmation or finality, the relay process, destination liquidity, exchange-rate movement, and the possibility that one stage fails. Relay Bridge addresses part of this problem through decentralized relay nodes that process transactions in parallel. Parallel processing can reduce bottlenecks, but it does not make blockchains identical or eliminate the need to wait for their own network conditions.

The platform describes typical transfer times of approximately two to five minutes. That is useful as an operating expectation, not a guarantee that applies equally to every asset, route, or period of congestion. A busy source chain can delay the initial transaction; a thin destination pool can increase slippage; and a network experiencing abnormal confirmation behavior can affect the overall route. A careful user should therefore treat speed as one variable in a route decision, alongside finality, liquidity, cost, and security.

What the bridge is actually doing

Relay Bridge uses hashed time-lock contracts, commonly called HTLCs. The mechanism relies on a secret and its cryptographic hash. In simplified form, a sender locks funds under conditions that allow the intended recipient or counterparty to claim them by presenting the secret before a deadline. If the required step does not occur within the time window, the funds can be returned according to the contract rules. This arrangement is designed to coordinate two chains without requiring a centralized custodian to hold and manually release the assets.

The important insight is that an HTLC creates conditional settlement, not universal safety. It can help ensure that a transfer does not remain indefinitely half-completed, and Relay Bridge states that failed transfers are automatically returned to the original chain when the established time limit expires. Yet the contract still depends on correct implementation, functioning networks, accurate transaction observation, and sufficient destination liquidity. A refund mechanism reduces one class of failure; it does not remove smart-contract risk, oracle or relay assumptions, market risk, or the possibility of operational delays.

For that reason, bridge security should be viewed as a layered system. The smart contracts must behave as intended. Relay nodes must communicate and process events correctly. The connected blockchains must remain sufficiently reliable. Liquidity providers must be willing to quote the route. Finally, users must select the correct asset and destination network. A bridge may be decentralized in its architecture while still exposing users to risks distributed across several independent layers.

Fees, liquidity, and the hidden price of convenience

Relay Bridge’s stated fee structure combines the source network’s gas fee with a variable bridge fee generally ranging from 0.1% to 0.5% of the transferred amount. That distinction is important for comparing routes. A percentage fee is relatively noticeable on a large transfer, while source-chain gas can dominate the economics of a small transfer. Conversely, on a congested Ethereum route, the gas component may matter more than the bridge fee itself.

The platform also describes dynamic algorithms that adjust to network congestion and may reduce cross-chain microtransaction costs by up to 90% compared with traditional atomic swaps or custodial solutions. The conditional wording matters. Such a saving depends on the route, transaction size, congestion level, liquidity, and comparison method. “Up to” is not an average, and lower execution cost does not necessarily mean lower total risk. A cheap transfer into a shallow market can produce more economic loss through slippage than a higher-fee route with deeper liquidity.

Liquidity providers are given a dual-yield incentive: rewards may include actual network gas tokens and the bridge’s native tokens derived from collected transaction fees. The Gas Token Index is described as distributing real gas tokens such as ETH, BNB, and MATIC while burning part of the fees. This structure attempts to make liquidity provision more tangible than a reward paid only in a project token. Still, the accounting should be read carefully. Token rewards can fluctuate in value, fee revenue depends on transaction activity, and liquidity providers can face inventory imbalance or losses when asset prices diverge across chains.

That is a useful correction to another common misconception: bridge liquidity is not free and it is not simply a pile of passive cash. It is an inventory positioned to satisfy users under changing market conditions. When one asset is heavily demanded in one direction, the pool’s composition changes. If arbitrage is slow or markets become disorderly, quoted prices may widen. The user sees this as slippage; the liquidity provider experiences it as exposure.

Why cross-chain collateral is powerful—and fragile

One of the more ambitious DeFi applications is cross-chain collateralization. In principle, a user can lock assets on one network and use them as collateral for lending or yield farming on another. This can improve capital access and reduce the need to sell an asset merely to participate in a different ecosystem. It also allows applications to specialize: one chain may offer inexpensive transactions, while another hosts a lending protocol with the desired market.

But collateral systems are only as strong as their cross-chain accounting. A lending protocol must know whether collateral was actually locked, whether it remains locked, and what happens if the bridge or connected network becomes unavailable. Price volatility adds another layer. If an asset’s value falls quickly on the source chain, or if its representation trades at a discount on the destination chain, liquidation can become more difficult. Cross-chain composability therefore expands financial flexibility while coupling systems that may fail at different speeds.

Users should also check whether a project imposes a token migration window. For certain assets, tokens that are not migrated before a stated deadline may become invalid under the project’s rules. This is not the same as an ordinary transfer expiry. A transaction timeout may return funds, while a migration deadline can affect whether a token remains recognized by an application. The practical lesson is simple: read the asset-specific instructions before approving a bridge transaction, especially during a contract upgrade or token migration.

A practical framework for choosing a route

A sensible bridge decision begins with purpose rather than speed. Ask what the destination asset will be used for, how long the funds can remain exposed to the route, and whether the amount justifies the combined gas and bridge costs. Then review the destination token carefully: symbol similarity is not proof of identical contract origin, and choosing the wrong network can create recovery problems even when the transfer itself completes.

For everyday use, a compact checklist is more valuable than a universal ranking. Confirm the source and destination chains; estimate gas and the variable bridge fee; inspect the expected amount after slippage; verify the transaction deadline; and keep the transaction identifier. For a large transfer, a small test transaction can reveal whether the route, wallet, and destination application behave as expected. It may cost more in aggregate, but it can limit the consequences of an address or network-selection error.

Relay Bridge’s public information describes expansion plans for Solana, Polkadot, Cosmos through IBC, Arbitrum, and Optimism during 2025–2026. If those integrations proceed, the key question will not be simply how many networks are listed. It will be whether the new routes provide reliable finality handling, adequate liquidity, clear asset representations, and transparent failure procedures. Solana and IBC-connected Cosmos environments, for example, introduce different technical and operational assumptions from the currently supported set. More connectivity is valuable only when the weakest link is understandable and manageable.

Recent material about a company called Relay has focused on online business banking, checking accounts, automated transfers, and savings tools. That news belongs to a separate financial-services context and should not be treated as evidence about the DeFi bridge’s performance, governance, or security. Keeping similarly named products distinct is a small but important research habit: in crypto, branding can travel faster than verification.

What to watch as bridges mature

The next stage of multi-chain DeFi will likely be judged less by headline transaction counts than by the quality of coordination. Useful signals include transparent route pricing, clear liquidity data, understandable timeout behavior, documented contract upgrades, and evidence that incidents can be contained rather than propagated. If Relay Bridge adds the planned networks while preserving these properties, its aggregator model could make fragmented liquidity more accessible. If expansion outpaces monitoring and risk controls, the same connectivity could create a larger surface for failure.

There is also a regulatory and operational consideration for US users. A decentralized protocol may reduce dependence on a centralized intermediary, but it does not automatically clarify tax reporting, consumer protection, sanctions exposure, or the legal status of every token and activity. Those questions vary by user and transaction, so technical permission should not be confused with legal or financial suitability. Before using the service, readers can consult the relay bridge official site for current route availability and operational details, then independently assess whether the route fits their needs.

The strongest mental model is to see a DeFi bridge as a negotiated boundary between systems, not as a pipe. It coordinates locked value, messages, liquidity, incentives, and deadlines. HTLCs and automatic reversals can improve the failure story; parallel relay nodes can improve throughput; dynamic pricing can improve efficiency. None of these features abolishes the underlying trade-off. Every bridge asks users to exchange some combination of cost, speed, liquidity, and trust assumptions. Understanding that exchange is the foundation of safer multi-chain participation.

FAQ: Relay Bridge and multi-chain DeFi

How long does a Relay Bridge transfer usually take?

Relay Bridge describes typical transfers as taking about two to five minutes. Actual timing can vary with source-chain congestion, confirmations, destination liquidity, relay activity, and the specific asset route. Treat the figure as a normal range rather than a guaranteed settlement time.

What fees should I expect?

The stated cost includes the source network’s gas fee plus a variable bridge fee generally ranging from 0.1% to 0.5% of the transferred amount. Before confirming, compare the total received amount, not just the percentage fee, because gas and slippage can materially change the economics.

Does an HTLC make a cross-chain transfer risk-free?

No. An HTLC can coordinate conditional settlement and support an automatic return if the transfer does not complete before its deadline. It does not eliminate smart-contract vulnerabilities, price slippage, connected-network attacks, relay failures, or user mistakes such as selecting the wrong destination network.

Why might someone use cross-chain collateral?

Cross-chain collateral can let users lock an asset on one network while using it in lending or yield-farming activity on another. The benefit is greater capital flexibility. The limitation is that the system becomes dependent on accurate cross-chain accounting, reliable pricing, and the continued operation of both the bridge and the DeFi application.
Career Opportunities at Qatar Shipyard_1

Career Opportunities at Qatar Shipyard

Our esteemed recruitment agency is pleased to announce an exclusive hiring initiative on behalf of Qatar’s Largest Shipyard. We are seeking highly motivated and experienced Skilled Workers to join their dynamic team for major ongoing and upcoming projects.
This is an exceptional opportunity to build a career with a world-class industry leader known for excellence and innovation in maritime and heavy industrial operations.
Position Available:
Skilled Workers
Employment Package & Benefits:
Competitive Salary: Negotiable, commensurate with Gulf experience and relevant certifications
Fully-Furnished Accommodation: Company-provided at no cost
Meals: Complimentary meals provided
Transportation: Company-sponsored transport services
Working Schedule: 8 hours per day with additional overtime opportunities
Candidate Requirements:
Proven work experience in Gulf countries (Qatar, Saudi Arabia, UAE) or significant local industry experience
Valid professional certification relevant to the applied role (mandatory)
In-depth knowledge and adherence to international health, safety, and environmental standards in industrial settings
Application Process:
Eligible and interested candidates are invited to submit their updated resumes along with scanned copies of relevant documents (including passport, certifications, and experience letters) via email for the initial screening process.
We look forward to welcoming skilled professionals ready
to grow with one of Qatar’s most prestigious industrial enterprises.
Connect With Us:
📧 Email: careers@manconint.com
📞 Call/WhatsApp: +92-370-815-6008
🌐 Official Website: www.manconint.com
Follow for more opportunities:
LinkedIn | Instagram | Facebook | WhatsApp Channel
📍 Office Address:
Office # 25, 2nd Floor, Center Point Plaza
Main Boulevard, Gulberg III
Lahore, Pakistan

We look forward to welcoming skilled professionals ready to grow with one of Qatar’s most prestigious industrial enterprises.

Trezor hardware wallet security depends on verifying transaction details on the device and protecting the recovery backup

Trezor Model T and Trezor Suite: What Hardware Wallet Security Actually Protects

What if the most important security decision is made before a Trezor is ever connected to a computer? For many users in Germany, the instinct is to focus on downloading Trezor Suite, choosing a device, and moving coins from an exchange. That sequence is understandable, but it can hide the real issue: a hardware wallet does not make every crypto action safe. It changes where critical decisions occur and who controls the private keys. The Trezor Model T is therefore best understood not as a magic vault, but as a signing device whose security depends on a chain of choices involving purchase, setup, backup, verification, and daily use.

Trezor, developed by the Czech company SatoshiLabs, is designed to keep private keys offline. The keys are used inside the device to sign transactions and are not exposed to the connected computer. Trezor Suite provides the management layer for accounts, balances, transfers, and selected functions such as buying, exchanging, or staking supported assets. The distinction matters: Suite is the interface, while the hardware device is the place where authorization is meant to happen.

Trezor hardware wallet security depends on verifying transaction details on the device and protecting the recovery backup

The central myth: offline keys do not mean offline risk

The strongest protection offered by a hardware wallet is against key exposure on a compromised computer. Malware may monitor the desktop, alter copied addresses, or attempt to deceive the user through a fake application. Because the private key remains on the Trezor and signing occurs there, an attacker cannot simply extract the key from the operating system in the same way that a software wallet may be exposed.

That protection has a boundary. A malicious computer can still prepare a transaction with the wrong recipient or amount. The hardware wallet cannot infer the user’s intention; it can only display transaction data and request confirmation. This is why the Model T’s screen is more than a convenience feature. It is a trusted display: the final address and amount should be checked on the device itself, not merely in Trezor Suite. If malware performs address swapping, the device display gives the user an opportunity to detect the substitution.

This produces a useful mental model: the computer proposes, the hardware wallet verifies and signs, and the human decides. If the user confirms without reading the device display, one of the most important security controls is effectively bypassed. The process is safer than relying on a hot wallet alone, but it is not automatic protection against careless approval, social engineering, or a user who has been persuaded that a fraudulent transaction is legitimate.

Downloading and setting up Trezor Suite without creating a new weakness

For the software step, users should obtain the official application through a trusted source rather than a sponsored search result, unsolicited message, or link supplied by a stranger. A practical starting point for the trezor suite download is to verify the source carefully before installation and to treat any unexpected request for sensitive information as a warning sign.

A legitimate Trezor Suite workflow is deliberately designed around the principle that the recovery seed should not be typed into a computer. The standard backup is a 24-word recovery phrase based on the BIP-39 standard. It can recreate the wallet on a compatible device, which is precisely why possession of the words is equivalent to possession of the funds. Trezor Suite should not ask users to enter this phrase through the computer keyboard. A request to do so may indicate phishing, counterfeit software, or a fraudulent support interaction.

The setup environment deserves the same attention as the application. A device bought from an unknown marketplace introduces a supply-chain risk: it may be counterfeit, altered, or previously initialized. Buying through official channels and examining the packaging and hologram seals are sensible controls. They do not prove absolute safety, but they reduce a class of attacks that software checks alone may not detect. If a device arrives already configured or someone provides a recovery phrase with it, it should not be treated as ready for use.

Model T, Model One, and the trade-off behind the portfolio

The Model T occupies a different position from the older Model One. Its touchscreen makes entering sensitive information and navigating confirmations more direct, and it supports Shamir Backup. Shamir Backup divides recovery material into several shares according to a chosen threshold, reducing the danger that one misplaced paper or metal backup becomes a single point of failure. This is useful for households or businesses that can store shares in separate secure locations.

However, a distributed backup is not automatically better. It introduces operational complexity: the owner must understand how many shares are required and where each share is stored. Losing too many shares can make recovery impossible, while careless labeling can reveal relationships between them. A simple single backup, protected properly and tested through a carefully controlled recovery plan, may be less error-prone for some individual users.

The Model One remains attractive as a lower-cost entry device, but its asset compatibility must be checked before purchase. In particular, the older model does not support certain well-known assets such as XRP and ADA in the same way as newer models. Broad claims that a wallet supports “thousands of coins” are therefore insufficient. Support can depend on the exact device, firmware, account type, token standard, and third-party integration. A German user building a portfolio beyond Bitcoin and Ethereum should make the asset list a purchase criterion, not an afterthought.

Open source, passphrases, and the limits of technical reassurance

Trezor’s open-source security model allows the software to be inspected by independent experts, which improves transparency and makes hidden functionality more difficult to conceal. That is a meaningful design advantage for users who value auditability. It is not the same as a guarantee that every vulnerability has been found or that every surrounding component is secure. Open code supports scrutiny; it does not eliminate implementation mistakes, supply-chain threats, or human error.

A passphrase, sometimes described informally as a “25th word,” can create an additional hidden wallet. The exact passphrase is essential: a small difference produces a different wallet, which means that forgetting it is functionally equivalent to losing access. Passphrases can provide stronger compartmentalization and plausible deniability, but they also increase the burden of documentation and recovery. They are best used by people who have a clear plan for storing and reproducing them, rather than as a fashionable extra layer.

The same reasoning applies to decentralized applications. Trezor can interact with DeFi platforms, NFT marketplaces, and services through WalletConnect or integrations with software wallets such as MetaMask. The private key may remain protected, but the user can still approve a dangerous smart-contract interaction. Hardware signing prevents key theft; it does not guarantee that a contract is honest, that an allowance is limited, or that an irreversible transaction has favorable consequences.

A practical security framework for German crypto users

Before sending meaningful value, it helps to separate four questions. First, is the device genuine and obtained through a trustworthy channel? Second, is the software authentic and installed without responding to an unsolicited prompt? Third, is the recovery backup created privately, stored offline, and understandable to the person who must recover it? Fourth, will every important transaction be checked on the device screen?

This framework is more durable than memorizing product features. It also reveals where the remaining risk sits. The hardware may reduce exposure of private keys, while the largest practical danger shifts toward seed theft, fraudulent support, incorrect backups, manipulated recipient addresses, and deceptive dApps. In other words, a hardware wallet often relocates risk rather than abolishing it.

Recent emphasis on transparent, open-source security reinforces this distinction. If users continue moving away from custodial platforms, control over assets increases, but so does responsibility for recovery and verification. A plausible near-term implication is that wallet education will become as important as device selection: the strongest product cannot compensate for a recovery phrase photographed to cloud storage or a transaction approved without reading the display.

Frequently asked questions

Is the Trezor Model T safer than keeping crypto on an exchange?

It changes the custody model rather than offering a universal safety ranking. The Model T keeps private keys under the user’s control and signs transactions on the device, reducing dependence on an exchange. The trade-off is that the user becomes responsible for backups, authentication decisions, device security, and recovery. If the seed is lost or exposed, customer support cannot simply reverse the outcome.

Can malware still steal funds when a Trezor is connected?

Malware should not be able to extract the private key from the device, but it may manipulate transaction details shown on the computer. The critical defense is to compare the recipient address and amount on the Trezor display before confirming. This control is effective only when it is actually used.

Should every user use Shamir Backup or a passphrase?

Not necessarily. Both features can reduce particular risks, but they add complexity. Shamir Backup is valuable when backup shares can be stored securely in separate places, while a passphrase is useful only if it can be reproduced reliably. For many users, a correctly created and carefully protected standard backup is safer than an advanced scheme they do not fully understand.

The most accurate conclusion is modest but important: Trezor Model T and Trezor Suite can create a strong separation between an exposed computer and the private key, yet the user remains part of the security mechanism. Buying authentically, installing cautiously, protecting recovery material, and reading the hardware display are not peripheral rituals. They are the system.

Uniswap DEX, Uniswap v3, and the Security Logic of Liquidity

A decentralized exchange can be most dangerous when it feels easiest to use. A trader may connect a wallet, approve a token, press “swap,” and see a quote in seconds—yet the transaction still depends on smart contracts, token permissions, blockchain selection, liquidity depth, and execution conditions. Convenience hides the system’s moving parts.

That tension defines Uniswap. As an automated market maker, or AMM, it replaces a traditional order book with token pools and mathematical pricing. For US users, the practical question is not simply whether Uniswap can exchange one asset for another. It is whether the selected pool, network, route, slippage limit, wallet approval, and token contract collectively provide an acceptable risk-adjusted trade. Uniswap v3 makes that judgment more important because its concentrated liquidity improves capital efficiency while making liquidity provision more active and less forgiving.

What a Uniswap swap actually depends on

In a conventional exchange, traders interact with visible bids and offers. Uniswap instead draws on liquidity pools: smart contracts holding two tokens. The basic pricing intuition comes from the constant-product relationship x × y = k, where the reserves of the two assets influence the exchange rate. When a trader removes one token from the pool, the transaction must add enough of the other token to preserve the pool’s pricing rule, subject to fees and the particular design of the deployed pool.

This is not a fixed-price vending machine. The larger the trade relative to available liquidity, the more the trade moves the pool price. That movement is price impact. Slippage is the difference between the expected and final execution price, which can also arise from market movement or intervening transactions before the user’s transaction is confirmed. A quote therefore describes a condition, not a guarantee.

Uniswap’s Universal Router can execute exact-input and exact-output swaps and handle more complex routing across available liquidity. That may improve execution, but routing sophistication does not remove the underlying risks. A route can still cross thin pools, incur network fees, interact with an unfamiliar token, or fail to meet the user’s minimum-output requirement. The router is an execution mechanism, not a substitute for verifying what is being traded.

Before approving a transaction, a careful trader should confirm the network, the token contract address, the direction of the trade, the expected minimum received, and the spender or contract receiving approval. A familiar ticker symbol is not proof of authenticity. On public blockchains, counterfeit tokens can copy names and branding with little friction.

Why Uniswap v3 changes liquidity provision

Uniswap v3 introduced concentrated liquidity. Instead of distributing capital across the entire possible price curve, a liquidity provider selects a price range. Capital inside that range is more active and can support trades with greater efficiency than the same capital spread broadly. The apparent advantage is straightforward: less idle capital and potentially more fee-generating activity around a chosen market price.

The less obvious consequence is that a v3 liquidity position is not passive in the same sense as holding two assets in a wallet. If price moves outside the chosen range, the position may become one-sided and stop earning fees from trades occurring outside it. A position that looked efficient at deposit can become poorly placed after a sharp market move. Range selection is therefore a forecast about where trading will occur, not merely a technical setting.

Consider an ETH-USDC position placed within a relatively narrow band. If ETH remains inside that band and trading volume is healthy, the provider may collect fees while supplying useful liquidity. If ETH rises through the upper boundary, the position may increasingly consist of USDC or the other side of the pair, depending on the direction of movement, and eventually become inactive for that range. Repositioning may restore activity, but it adds transaction costs, timing risk, and operational complexity.

This creates a critical distinction between fee yield and economic return. Fees are visible and measurable, while impermanent loss is comparative: it describes how the liquidity position performs relative to simply holding the deposited assets. If the tokens diverge substantially in price, the pool’s rebalancing mechanism can leave the LP with a different asset mix than a passive holder would have retained. Fees may offset that difference, but they do not automatically eliminate it.

Liquidity is an operational exposure, not just a balance

For traders, deeper liquidity can reduce price impact. For LPs, however, depositing capital means accepting several exposures at once. There is smart-contract risk, token-specific risk, market-direction risk, range-management risk, and network risk. A pool can be technically functioning while still producing an unattractive result for a particular LP.

Uniswap v4 extends the design space through hooks, which allow custom logic around pools. Hooks can support dynamic fees, time-weighted pricing mechanisms, or other customized behavior. This flexibility may enable better market design, but it also enlarges the surface that users must understand. A pool’s label or fee tier is not enough information to evaluate a position when additional logic can affect how the pool behaves.

Security review reduces risk; it does not convert risk into certainty. The protocol’s security efforts have included formal audits, a major security competition, and a bug bounty program. Those measures are meaningful signals of scrutiny, but audits are not guarantees against implementation mistakes, economic exploits, malicious tokens, compromised interfaces, or user error. The security boundary includes every contract and interface involved in the transaction.

Flash swaps illustrate why mechanism-level thinking matters. They allow tokens to be taken from a pool without upfront capital on the condition that the borrowed assets and fee are returned within the same transaction. This can support arbitrage and other capital-efficient strategies, but the same composability can amplify the consequences of a flawed integration or faulty assumption. A protocol feature may be legitimate while a strategy built around it remains highly risky.

A practical risk framework for swapping on Uniswap

A useful framework is to separate four questions. First, what asset is this? Verify the contract address and network rather than relying on the symbol. Second, where is the liquidity? Inspect the pool and route, especially for large trades or less-established tokens. Third, what is the worst acceptable execution? Set a minimum received amount or maximum spend that reflects the trade’s purpose, while recognizing that an excessively tight limit can cause failure. Fourth, what permissions remain afterward? Token approvals can persist beyond the immediate swap and should be reviewed as part of wallet hygiene.

Network choice is also a trade-off. Ethereum mainnet may offer substantial liquidity for some pairs but can impose higher transaction costs. Layer 2 networks and other supported chains may reduce fees and improve accessibility, yet liquidity, token availability, bridging assumptions, and operational familiarity can differ. A cheaper transaction is not automatically a better transaction if the selected network has thinner liquidity or the user sends assets to the wrong chain.

Self-custody changes the responsibility model. The Uniswap Wallet includes built-in swapping, clear-signing features, Secure Enclave storage for private keys, and cross-chain functionality on supported networks. These features can make transaction details easier to inspect and keys harder to extract from the device, but they do not protect a user who approves a malicious contract or confirms a deceptive transaction. Hardware and interface safeguards help; deliberate verification remains necessary. Readers who need a starting point for checking the interface can review uniswap, but should still verify domains and transaction details independently.

What the recent multi-chain emphasis means

This week’s project messaging highlights buying, selling, and trading Ethereum and other major tokens across Ethereum, Base, Arbitrum, Polygon, Unichain, and additional networks. The practical implication is broader access, but not uniform market quality. “Available across chains” should be read as an invitation to compare execution environments, not as evidence that every asset or pool has equivalent depth and reliability.

If multi-chain activity continues to expand, the important signal will be whether users can understand the differences between routes without treating the experience like a single centralized venue. Liquidity fragmentation, bridge dependencies, changing gas costs, and chain-specific contract deployments all remain relevant. The more networks an interface supports, the more valuable clear signing and explicit network confirmation become.

Governance adds another layer. UNI holders participate in decisions involving protocol upgrades, fee structures, and ecosystem development. Governance can shape incentives and technical direction, but token governance should not be confused with a guarantee of individual trade outcomes. A vote can change parameters or authorize development without removing market, custody, or smart-contract risk.

Frequently asked questions

Is Uniswap safer than a centralized exchange?

It has a different risk profile rather than a universally safer one. Users retain custody and interact directly with smart contracts, which reduces dependence on an exchange account but increases responsibility for seed phrases, approvals, token verification, slippage, and transaction signing. Centralized platforms introduce custodial and account risks instead.

Why can a Uniswap v3 liquidity position stop earning fees?

Concentrated liquidity earns trading fees only while the market price remains within the selected range and the position is active for that trading interval. If price moves outside the range, the position may become inactive until price returns or the provider changes the range.

Does earning fees remove impermanent loss?

No. Fees can compensate for some of the economic effect, but the result depends on trading volume, fee rate, price divergence, range selection, rebalancing costs, and the duration of the position. A high fee rate alone is not proof of a profitable LP strategy.

What is the most important check before a large swap?

Verify the token contract and network, compare the quoted route with available liquidity, set a defensible slippage limit, inspect the transaction and approval request, and consider splitting the trade if price impact is material. The goal is not merely to make the transaction succeed, but to ensure that success means what you intended.

Uniswap’s central lesson is that liquidity is not an invisible utility and a swap is not a simple button press. The protocol turns market making into software, exposing both powerful efficiency and precise failure modes. Traders who understand reserves, ranges, routing, approvals, and execution limits can use the system more intelligently. LPs must go further: they must treat a position as an active, market-sensitive strategy whose fees are compensation for risk, not free income.

Structural Welding Supervisor

Urgent Hiring: Structural Welding Supervisor (Oil & Gas – Offshore)

Experience Required: 10+ years
Previous Title: Supervisor or Foreman (min. 5 years)
Mandatory Experience & Skills:
Oil & Gas Experience: Minimum 10 years of offshore construction experience, specifically in Topside and Jackets.
Must have a strong background as a Structural Welder for at least 3 years.
Soft Skills: Excellent English communication and computer skills (email, reporting).
Stay Connected With Us:
Official Website:
www.manconint.com
LinkedIn: https://lnkd.in/d6KdK5N8
Instagram: instagram.com/ManconInt
Facebook: facebook.com/ManconInt
WhatsApp Channel: https://lnkd.in/dWVxWMVT
Your global career journey starts here.
Follow us for the latest job opportunities and career insights!

Structural Fitting Supervisor

Urgent Hiring: Structural Fitting Supervisor (Oil & Gas – Offshore)

Experience Required: 10+ years
Previous Title: Supervisor or Foreman (min. 5 years)
Mandatory Experience & Skills:
Oil & Gas Experience: Minimum 10 years of offshore construction experience, specifically in Topside and Jackets.
Must have a strong background as a Fitter for at least 3 years.
Technical Knowledge: Must be well-versed in the process of steel heating.
Soft Skills: Excellent English communication and computer skills (email, reporting).
Stay Connected With Us:
Official Website:
www.manconint.com
LinkedIn: https://lnkd.in/d6KdK5N8
Instagram: instagram.com/ManconInt
Facebook: facebook.com/ManconInt
WhatsApp Channel: https://lnkd.in/dWVxWMVT
Your global career journey starts here.
Follow us for the latest job opportunities and career insights!

Painting Supervisor

Urgent Hiring: QFAB Supervisors (Oil & Gas – Offshore)

Painting Supervisor
Experience Required: 8+ years in industrial painting, specifically in Oil & Gas
Previous Title: Painting Supervisor (min. 2 years) or Senior Painting Foreman (min. 10 years)
Key Responsibilities:
Supervise all surface preparation and application of protective coatings on offshore structures, including Topside modules, Jackets, and subsea components.
Ensure all painting activities meet project specifications, technical data sheets, and ISO standards.
Conduct inspections (DFT, adhesion tests) to guarantee coating quality and longevity.
Manage paint materials, including inventory, mixing, and application, minimizing waste.
Lead and train crews in safe and effective blasting and painting techniques, with a strong emphasis on HSE procedures due to the hazardous nature of the work.
Collaborate with construction and QA/QC teams to ensure proper sequencing and inspection of painted surfaces.
Mandatory Experience & Skills:
Oil & Gas Experience: Minimum one year of experience in Offshore Topside & Jackets or subsea structure painting is mandatory.
Technical Knowledge: In-depth knowledge of paint materials (epoxy, polyurethane, zinc), surface preparation standards (SA 2.5, SA 3), and application methods (airless spray).
Note: This role is focused on new construction coating, not maintenance. Candidates with only refinery maintenance experience will not be considered.
Soft Skills: Excellent English communication and computer skills.
Stay Connected With Us:
Official Website:
www.manconint.com
LinkedIn: https://lnkd.in/d6KdK5N8
Instagram: instagram.com/ManconInt
Facebook: facebook.com/ManconInt
WhatsApp Channel: https://lnkd.in/dWVxWMVT
Your global career journey starts here.
Follow us for the latest job opportunities and career insights!

Piping Supervisor

Urgent Hiring: QFAB Supervisors (Oil & Gas – Offshore)

Piping Supervisor
Experience Required: 10+ years in Oil & Gas construction
Previous Title: Piping Supervisor (min. 2-3 years) or Senior Piping Foreman (min. 10-15 years)
Key Responsibilities:
Lead and supervise a team of pipefitters and technicians in all phases of offshore piping installation, fabrication, and hydrotesting.
Read and interpret isometric drawings, P&IDs, and structural drawings to plan and execute work efficiently.
Oversee the installation of deck piping systems, risers, and associated supports on offshore Topside modules and Jackets.
Manage and execute hydrostatic and pneumatic testing procedures, ensuring strict adherence to safety protocols and quality standards.
Coordinate with other discipline supervisors (structural, welding, painting) to ensure seamless project integration and progress.
Monitor work progress against project schedules, allocate resources effectively, and report daily to the project manager.
Enforce strict compliance with all company and client HSE policies, conducting toolbox talks and risk assessments.
Mandatory Experience & Skills:

Oil & Gas Experience: Minimum 2-3 years of direct experience in Offshore Topside & Jackets construction is mandatory.
Must have extensive hands-on experience with:
Pipe Fabrication & Installation: Deck piping, risers, spools, and supports.
Hydrotesting: Developing test packs, conducting tests, and documenting results.
Soft Skills: Fluent English communication (verbal and written), strong computer skills for email and reporting, proven leadership and team management abilities.
Stay Connected With Us:
Official Website:
www.manconint.com
LinkedIn: https://lnkd.in/d6KdK5N8
Instagram: instagram.com/ManconInt
Facebook: facebook.com/ManconInt
WhatsApp Channel: https://lnkd.in/dWVxWMVT
Your global career journey starts here.
Follow us for the latest job opportunities and career insights!

Career Opportunities At Qatar Shipyard

Career Opportunities At Qatar Shipyard

Project: QFAB
Location: Qatar
Status: Urgent – Immediate Start Required
1. Piping Supervisor
Experience Required: 10+ years
Previous Title: Supervisor (min. 2-3 years) or Foreman (min. 10-15 years)
Mandatory Experience & Skills:
Oil & Gas Experience: Minimum 2-3 years of onshore/offshore experience in Topside & Jackets is mandatory.
Must have hands-on experience with:
Deck & Risers
Hydrotesting
Pipe Installation
Pipe Fabrication
Soft Skills: Excellent English communication and computer skills (email, reporting).
2. Painting Supervisor
Experience Required: 8+ years
Previous Title: Supervisor (min. 2 years) or Foreman (min. 10 years)
Mandatory Experience & Skills:
Oil & Gas Experience: Minimum one year of experience in the following is mandatory:
Topside and Jackets painting operations.
Subsea structure painting.
Technical Knowledge: Basic paint material knowledge and application experience is essential.
Note: This role is for new construction, not maintenance. Candidates with only refinery experience will not be considered.
Soft Skills: Excellent English communication and computer skills (email, reporting).
3. Structural Fitting Supervisor
Experience Required: 10+ years
Previous Title: Supervisor or Foreman (min. 5 years)
Mandatory Experience & Skills:
Oil & Gas Experience: Minimum 10 years of offshore construction experience, specifically in Topside and Jackets.
Must have a strong background as a Fitter for at least 3 years.
Technical Knowledge: Must be well-versed in the process of steel heating.
Soft Skills: Excellent English communication and computer skills (email, reporting).
4. Structural Welding Supervisor
Experience Required: 10+ years
Previous Title: Supervisor or Foreman (min. 5 years)
Mandatory Experience & Skills:
Oil & Gas Experience: Minimum 10 years of offshore construction experience, specifically in Topside and Jackets.
Must have a strong background as a Structural Welder for at least 3 years.
Soft Skills: Excellent English communication and computer skills (email, reporting).
What We Offer For All Positions:
Competitive Monthly Salary: QAR 8,000 (All-inclusive)
The opportunity to work on a significant offshore project.
A professional and challenging work environment.
Application Process:
Interested candidates are requested to follow our official page for updates and submit their updated resume to:
📧 careers@manconint.com
đŸ“± +92-370-815-6008
Join us and be part of an international workforce with Mancon International – Your trusted partner in global career opportunities.